Why Your Choice of Bank Affects Your GPT Payouts
If you earn through surveys, offers, games, or cashback and cash out surveys Canada-style via Interac e-Transfer, the account receiving that money matters more than most people assume. A single $10 payout barely tests your bank's limits, but GPT earners rarely stop at one — you might pull in five, ten, or twenty Interac e-Transfer GPT payouts a month from platforms like Cashsprint. Small frictions compound over time: a per-transfer cap that forces a wait, a hold that delays access to money you've already earned, or a monthly fee quietly eating into your side income.
The real decision isn't between "good" and "bad" banks, but between three account structures: traditional big banks, member-owned credit unions, and digital-first neo-banks. Each handles Interac e-Transfer receiving differently and has a distinct relationship with deposit insurance. Understanding those differences before you set up autodeposit will save you from discovering the limits mid cash-out, with earnings sitting in limbo.
Big Banks: Familiar but Often More Restrictive
RBC, TD, CIBC, BMO, and Scotiabank remain the default choice for most Canadians, with real comfort in that familiarity — branches, established apps, decades of trust. But big bank Interac e-Transfer limits weren't designed with frequent micro-payouts in mind. Receiving limits are generally fine for occasional transfers, yet the experience can create friction for someone cashing out repeatedly.
Some big banks apply daily or per-transfer caps that rarely bother a single paycheque deposit but can feel restrictive if you're stacking several GPT payouts the same day. Autodeposit is supported across all five major banks, but app notifications can lag, and security holds on incoming transfers — while uncommon — do happen, particularly on new accounts or unusual transaction patterns. If your GPT earnings are modest and occasional, a big bank account works fine. If you're cashing out frequently, fee structures (many big bank accounts still charge monthly fees unless you maintain a minimum balance) start to matter.
Credit Unions: Higher Limits, Local Trust, Provincial Insurance
Credit unions are member-owned, provincially regulated financial cooperatives that consistently punch above their weight for Interac e-Transfer receiving. Many offer higher — or even uncapped — receiving limits than the big banks. Steinbach Credit Union, for example, places no cap on the amount it will let you receive, exactly the kind of headroom a busy GPT earner wants. Many credit unions also skip monthly fees on basic chequing accounts, especially for members who bank primarily online.
The one question that trips people up: credit union deposit insurance is provincial, not CDIC. That's a structural fact, not a warning sign. Each province runs its own credit union deposit insurer — FSRA in Ontario, CUDIC in British Columbia, and CUDGC in Alberta and Saskatchewan, among others. Coverage terms vary by province, but several — including BC's CUDIC — guarantee the full value of eligible deposits with no dollar limit, arguably stronger protection than CDIC's standard caps. A narrow exception: a small number of federally regulated credit unions fall under CDIC coverage instead of provincial insurance, so confirm which regime applies to your institution. Either way, your GPT earnings sitting in a credit union account are genuinely well protected.
Desjardins, Canada's largest credit union network, illustrates the scale these institutions can reach — not a small, fringe alternative to mainstream banking, but a full-service option with competitive Interac e-Transfer handling.
Neo-Banks: Built-in Digital Convenience
EQ Bank, Tangerine, Simplii Financial, KOHO, and Wealthsimple Cash are often lumped in with credit unions because they feel similarly modern and fee-light. They aren't credit unions, though — most are digital divisions of federally regulated, CDIC-insured banks. Tangerine is a division of Scotiabank; Simplii Financial operates under CIBC. EQ Bank is a digital brand of Equitable Bank, a federally regulated Schedule I bank, and deposits there are CDIC-insured. KOHO and Wealthsimple Cash use partner-bank arrangements that also route eligible deposits into CDIC coverage.
Where neo-banks earn their keep is convenience for a GPT earner's cash-out routine. The EQ Bank e-Transfer limit for receiving is generous, notifications tend to be near-instant, and there are no monthly fees or minimum balance requirements to juggle. Tangerine and Simplii offer similarly clean, no-fee structures built for people who bank almost entirely through an app. If your goal is a dedicated account purely for receiving Interac e-Transfer payouts — one you check on your phone, not one tied to a mortgage or line of credit — neo-banks are built for exactly that use case.
Side-by-Side: What Actually Matters for GPT Earners
Rather than comparing every feature banks advertise, focus on the five things that actually affect a GPT payout routine:
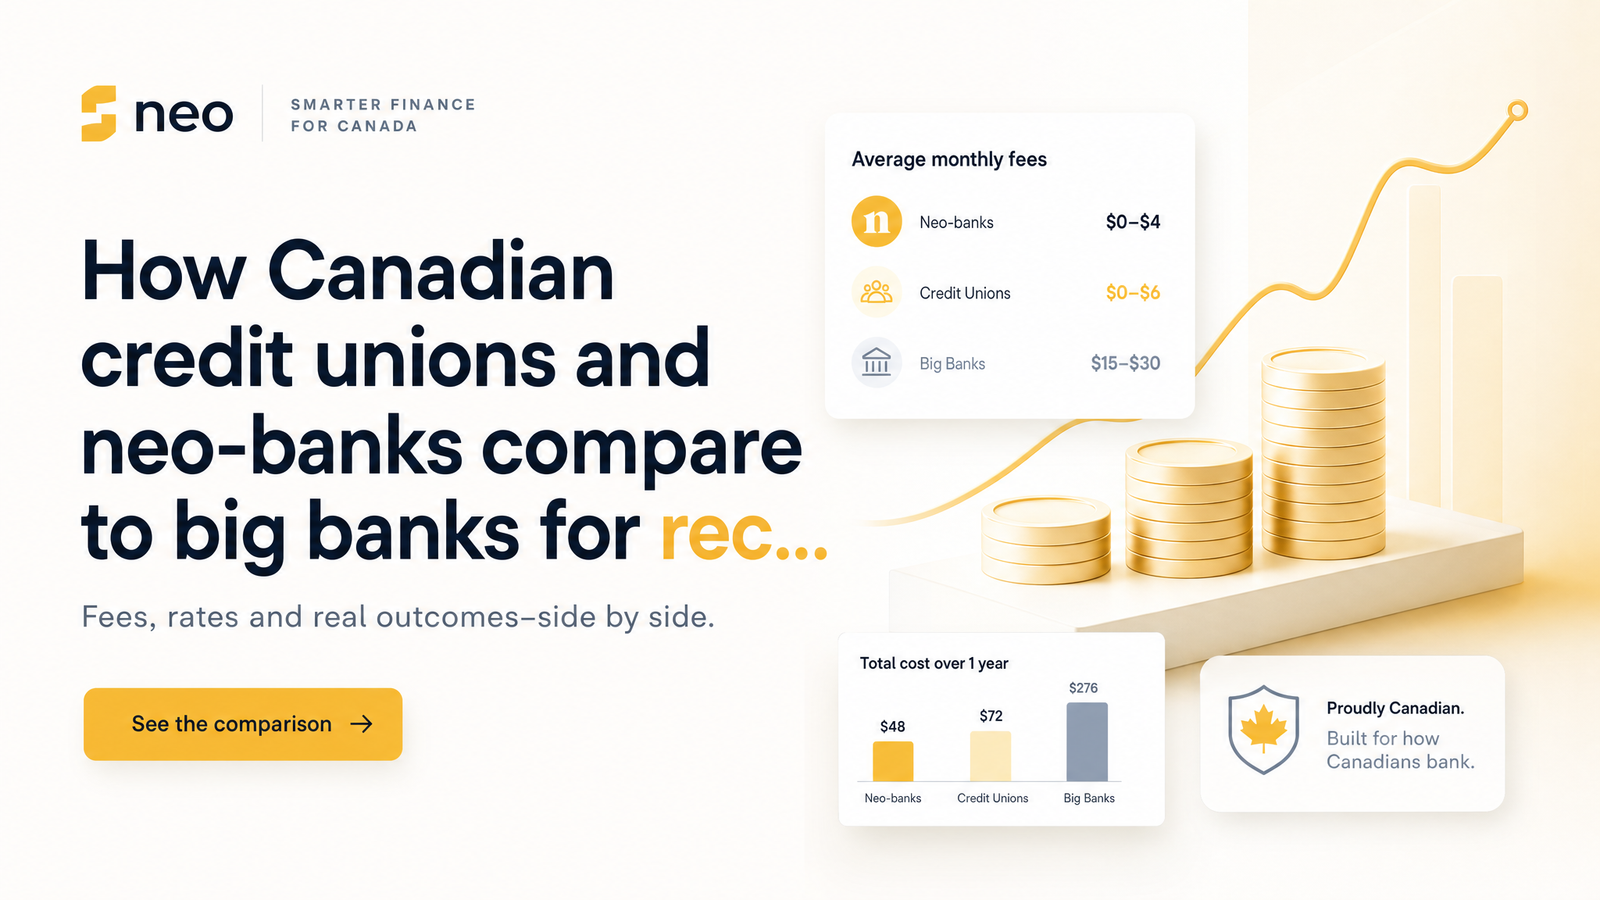
- Receiving limit per transfer/day: Credit unions often lead here, with some offering uncapped receiving. Neo-banks like EQ Bank and Tangerine offer high, clearly published limits. Big banks vary by institution and account type — see the full limits comparison from WOWA for exact figures across major institutions.
- Fees: Many credit unions and virtually all neo-banks skip monthly fees on basic accounts. Big banks often require minimum balances to waive them.
- Autodeposit reliability: All three types support Interac autodeposit, but neo-banks tend to push instant notifications, while some big bank apps lag by minutes.
- Deposit insurance type: Big banks and neo-bank partner banks are CDIC-insured. Credit unions are provincially insured (with rare federal exceptions), often with equal or stronger coverage.
- Everyday convenience: Big banks and Desjardins offer branches and full banking suites; neo-banks and many credit unions are app-first.
For the best bank for GPT payouts Canada-wide, there's no single universal winner — it depends on your volume. Someone cashing out twice a month can use almost anything. Someone cashing out weekly across multiple GPT platforms benefits from the higher receiving limits credit unions and neo-banks offer.
How to Decide: A Simple Framework
Start with volume. If you cash out from Cashsprint and similar platforms only occasionally, your existing big bank account is probably fine — no need to open something new for a few transfers a month. If you're cashing out weekly or hold multiple GPT and cashback sources feeding the same account, a credit union or neo-bank with a high or uncapped receiving limit removes the friction entirely.
Next, decide between an all-in-one bank and a dedicated cash-out account. Some earners prefer keeping GPT income mixed with their main chequing account for simplicity. Others open a second, fee-free account — often a neo-bank or credit union — purely as a landing zone for side-income transfers, then move funds manually once a month. This separation makes it easier to track how much your side hustle is actually generating.
Whichever you choose, set up autodeposit Interac e-Transfer correctly from day one. In your banking app, register the email address or phone number you use for Cashsprint payouts under Interac e-Transfer settings, confirm autodeposit is switched on (not just "available"), and verify the registration with a small test transfer if your platform supports it. Skipping this step is the single most common reason GPT earners miss a payout notification or have a transfer expire before they manually accept it.
Once your receiving account is sorted, the next practical step is comparing how fast each payout method actually lands — Interac e-Transfer generally outpaces PayPal and gift cards for speed, as broken down in Cashsprint's payout options ranked by speed. If you're still building confidence in the platform itself, this evidence-based review of Cashsprint is a useful reality check before you commit real time to it.
Frequently Asked Questions
Are credit unions covered by the same deposit insurance as banks?
No — credit unions are typically covered by provincial deposit insurers rather than the federal CDIC that protects big banks. Ontario uses FSRA, British Columbia uses CUDIC, and Alberta and Saskatchewan use CUDGC, and coverage terms differ by province. A small number of federally regulated credit unions are CDIC-insured instead, so check which applies to your institution.
Can I use a neo-bank like EQ Bank or KOHO to receive Cashsprint payouts?
Yes, neo-banks like EQ Bank, Tangerine, Simplii, KOHO, and Wealthsimple Cash all support Interac e-Transfer receiving and autodeposit, making them well suited to frequent GPT cash-outs. They're divisions or partners of CDIC-insured banks, not independent credit unions, but deposits are still protected.
Do credit unions charge fees to receive Interac e-Transfers?
Most credit unions do not charge a fee specifically to receive an Interac e-Transfer, and many also waive monthly account fees on basic chequing products. Always confirm the exact fee schedule with your specific credit union, since terms vary by province and institution.
Which is better for frequent GPT payouts: a credit union or a big bank?
For frequent payouts, credit unions generally have the edge because many offer higher or uncapped receiving limits and fee-free basic accounts. Big banks remain a reasonable choice for occasional cash-outs but can feel more restrictive once you're receiving multiple transfers a week.
Is my money less safe at a credit union than at a big bank?
No, money at a credit union is not inherently less safe — it's insured under a different, provincial system rather than CDIC, and in provinces like British Columbia that insurance covers the full deposit with no dollar cap. The distinction is structural, not a measure of risk.
How do I set up autodeposit so I never miss a GPT payout?
Open your banking app's Interac e-Transfer settings and register the email or phone number linked to your Cashsprint account, then confirm autodeposit is actively turned on rather than merely available. Doing this before your first cash-out prevents transfers from sitting unclaimed or expiring.
Pick the account type that matches how often you cash out, switch on autodeposit before your next payout, then open a Cashsprint account and send your first survey or offer earnings straight to it via Interac e-Transfer — and once you're set up, these tips for maximizing your Cashsprint earnings are the natural next read.